Jon Bond

Small Island, Big Ideas


Tag: guernsey

  • The GST Debate Goes to Half-Time: What Three Days in July Actually Settled

    The GST Debate Goes to Half-Time: What Three Days in July Actually Settled

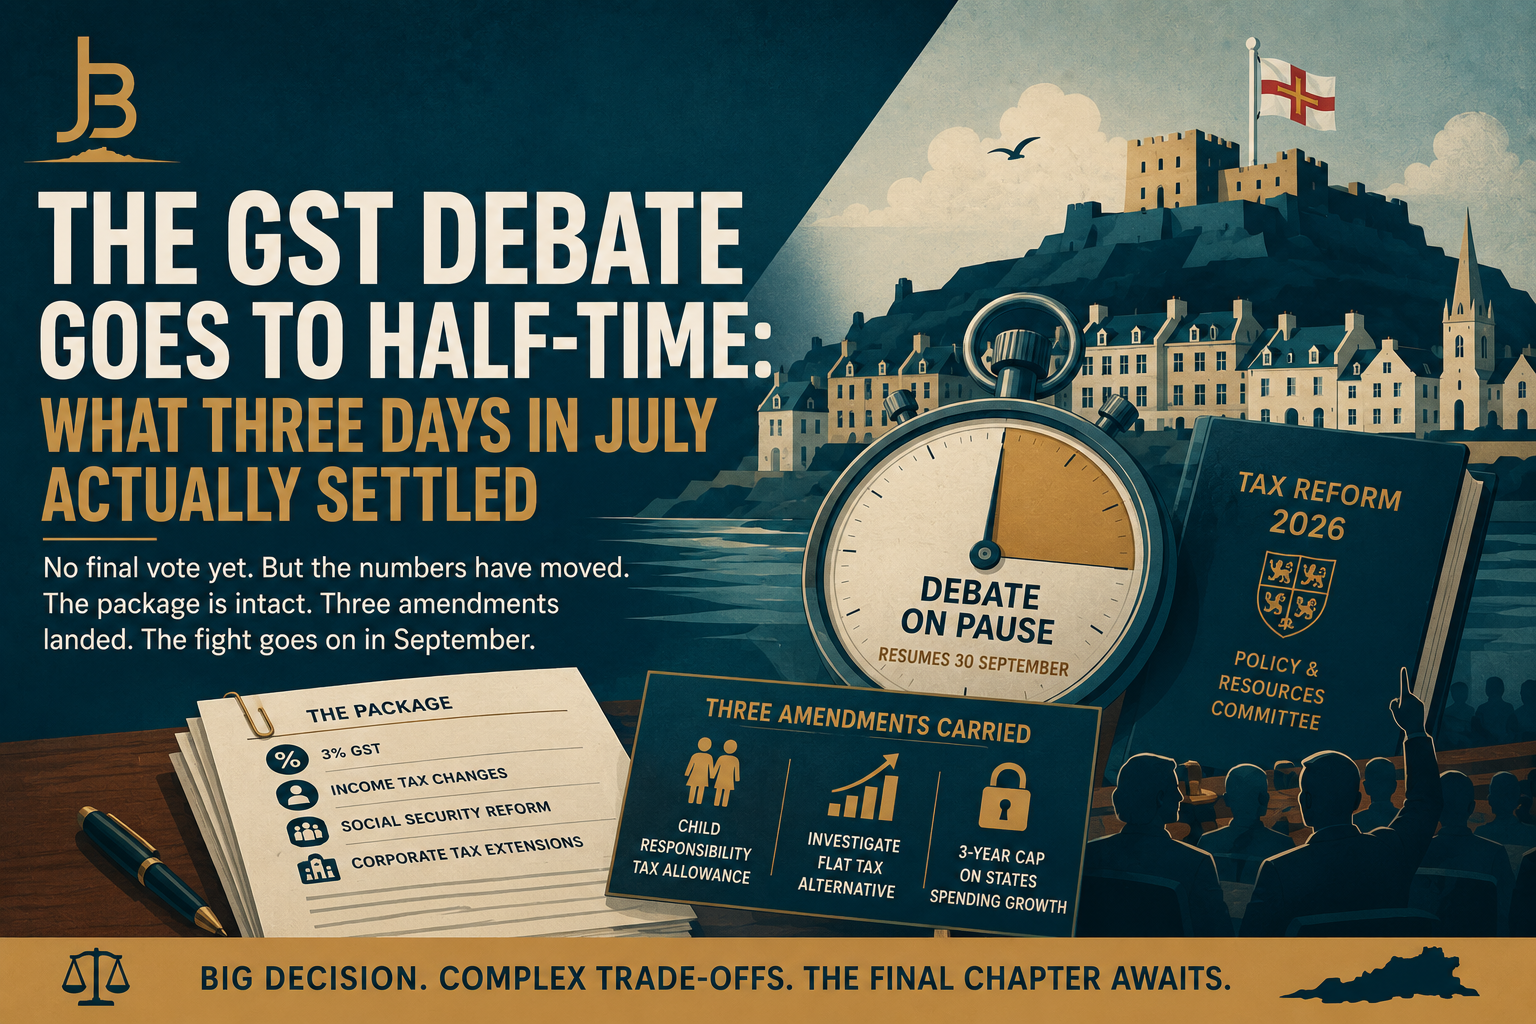
    Guernsey’s biggest tax decision in a generation is now on a summer break. After three days of debate on 15–17 July, the States ran out of road before reaching a final vote on Policy & Resources’ tax reform package — the 3% GST, the accompanying income tax and social security changes, and the corporate tax extensions attached to it. Deputies will pick it back up on 30 September.

    That pause is worth reflecting on. Nothing has been decided, but a lot has already happened, and the shape of what’s left to debate has changed in ways that matter more than the headline “no vote yet” suggests.

    What was actually on the table

    P&R’s package, published in June, centres on a 3% GST alongside higher income tax allowances, a reformed lower income tax band, and modest extensions to corporate tax — including bringing the 10% rate to cover the full profits of regulated businesses. Taken together, the committee says the package raises about £42m a year gross, or roughly £39.5m net once running costs are stripped out. That is the number to hold onto, because most of what follows is a fight over how that £39.5m gets found and who carries it.

    The kill shots that didn’t land

    Three attempts to stop the package outright were all defeated in the first two days:

    • A sursis from Deputy Liam McKenna and Deputy Mark Helyar to delay the whole debate, pending a new States Treasurer’s advice and a clear-out of the Revenue Service’s backlog, fell narrowly, 17 votes to 22.
    • An amendment to drop GST from the package entirely (McKenna) was defeated more heavily, roughly 28 votes to 10.
    • A call for a binding referendum on GST (McKenna and Simon Vermeulen) was rejected 25 votes to 14.
    • A separate bid to scrap the package for a new Appropriations Committee tasked with finding savings first (Garry Collins and Haley Camp) lost 29 votes to 11.

    P&R came out of those votes able to say, fairly, that its core proposition is intact. Treasury lead Charles Parkinson told the Press he believed there was “clearly a majority in favour” of the package; P&R President Lindsay de Sausmarez was more circumspect but agreed the numbers looked to be there. Neither claim has been tested – the substantive vote hasn’t happened, but the pattern of the July votes doesn’t contradict it.

    What did land

    Three amendments were carried, and each of them changes what P&R will actually be implementing if the package eventually passes:

    1. A Child Responsibility Tax Allowance (Andy Sloan and Munazza Malik) – a direction to P&R to introduce a new income tax allowance for each dependent child. This wasn’t a request for a report; it was an instruction. Gavin St Pier made the sharper point in debate: this is a directive, not a study, and the most likely funding source for it is more revenue – quite possibly more GST.
    2. An instruction to investigate a flat tax rate as an alternative structure.
    3. A three-year cap on growth in total States expenditure, including social security spending, to inflation (Sloan, moved by Helyar in his absence), which passed by the narrowest margin of the sitting, 15 votes to 12.

    The spending cap is the one worth watching. It was framed as a discipline measure, but its scope, explicit inclusion of social security spending, not just departmental budgets, has already drawn a public warning from the Committee for Health & Social Care that it risks real-terms cuts to services, and Bailiwick Express has since run a fact-check on the more alarmist claims doing the rounds about pensions being at risk (their verdict: the amendment doesn’t force pension cuts, but it does tie ESS’s hands in a way that could force difficult trade-offs). This is exactly the kind of measure that sounds costless in a sound bite and isn’t: capping headline spending growth to inflation while service demand, health and care in particular, runs ahead of inflation is a structural squeeze, not a saving.

    There’s a genuine tension buried in July’s results that P&R will have to reconcile before September: deputies voted, in the same sitting, to add a new tax allowance (a cost) and to cap spending growth (a constraint on where new costs get absorbed). Both carried. Neither amendment’s proposers were required to reconcile them with each other, and it’s not obvious P&R’s £39.5m net figure survives both being implemented as instructed.

    The procedural oddity

    Under the Assembly’s normal rules, adjourned debates don’t reopen for new amendments. Officials have indicated they’ll take a different view here, effectively reopening the amendment window until 22 September – which all but guarantees the 22 amendments considered in July will be added to before the Assembly reconvenes. Deputies campaigning against GST, including Garry Collins, have already signalled they’re preparing further amendments over the recess.

    Reading the numbers

    The vote margins across July tell a story in themselves. The sursis and the flat “no GST” amendment both lost by comfortable double-digit margins – this is not an Assembly on the verge of rejecting reform outright, in the way it did in 2023. But the spending cap amendment passing 15–12 is a different kind of signal: on a genuinely contested, ideologically loaded question about the size and shape of government, the numbers are close enough that a handful of switched votes moves outcomes. If the substantive GST vote in September comes down to a margin like that, this is not settled business, whatever the confidence from Treasury and P&R leadership suggests.

    What to watch for in September

    • Whether P&R chooses to adjust its own package before the debate resumes, as de Sausmarez has hinted is possible, rather than defend it unamended against a fresh round of amendments.
    • How P&R proposes to reconcile the child tax allowance and the spending cap, both now carried, both pulling in opposite directions on the same £39.5m.
    • Whether the reopened amendment window produces anything that changes the arithmetic, rather than simply adding volume to an already long list.
    • The roughly ten to eleven amendments left over from July that still haven’t been debated at all.

    None of this changes the structural point that’s been the throughline of this year’s tax debate: Guernsey has a funding gap that isn’t going away, reserves that are being run down to cover it, and a package on the table that raises real revenue but does so by reshaping who pays and how. Three days in July didn’t answer whether the States will accept that reshaping. It mostly confirmed that the fight over the details, allowances, caps, who bears the transition, may end up mattering as much as the headline GST number itself.

    Sources: Guernsey Parliament (parliament.gg), States Meeting 15 July 2026, Billet d’État XII; Guernsey Press, 15–22 July 2026 and 17 August 2026; Bailiwick Express, July 2026; States of Guernsey, “2026 Tax Reform Package published.”

    Jon Bond is Founder and CEO of Evans Bond Limited, an accountancy and advisory practice in Guernsey, and principal of Melius Consulting Limited – a business consultancy. He is also a non-executive chairman of CI Co-op and Sark Shipping. The views expressed here are his own.

  • GST – The Big Debate

    GST – The Big Debate

    Deputies will spend part of this sitting debating the Policy & Resources Committee’s Tax Reform 2026 package – the outcome of the Tax Review Sub-Committee’s work on making the Bailiwick’s finances more sustainable.

    It’s rarely a single up-or-down vote on something this size: one member has proposed shelving it entirely (a “Sursis”), and 22 separate amendments have been laid, ranging from small technical exemptions to wholesale replacements of the entire package.

    This post summarises the core proposal and every amendment that’s been laid, and gives you a searchable table to explore them.

    The Main Proposal

    Brought by the Policy & Resources Committee, the proposition asks the States to agree, having considered the Policy Letter “Tax Reform 2026” dated 8 June 2026:

    • To direct the Committee to implement the package of tax reforms set out in sections 9 and 10 of the Policy Letter, covering income tax, social security contributions, a goods and services tax (GST) and other measures, with rates and thresholds as set out in Appendix 7.
    • To add the Tax Reform Programme to the Major Projects Portfolio and delegate authority to Policy & Resources to approve up to £10.6m of implementation funding from the General Revenue Reserve, subject to business cases.
    • To direct Policy & Resources to return to the States with an assurance review in 2030 (section 12).
    • To direct preparation of the legislation necessary to give effect to the above.
    Ref Category What it does Proposers
  • Guernsey’s Tax Reform 2026: What It Actually Says, and What It Doesn’t

    Guernsey’s Tax Reform 2026: What It Actually Says, and What It Doesn’t

    After years of Green Papers, Billets, rejected amendments, and deferred decisions, the States of Deliberation are again being asked to vote on a substantive, costed tax reform package. The Policy Letter published this week is the culmination of over a decade of deliberation, and whatever you think of the conclusions, it is a serious piece of work that deserves a serious read.

    So let me try to give you that.

    The Problem They’re Trying to Solve

    The starting point is not in dispute. Guernsey has been running a structural deficit for several years — spending has consistently outpaced revenue, and reserves have been used to paper over the gap. The 2026 Budget estimate puts the structural deficit at around £77 million a year, and that figure is calculated after factoring in the expected £40 million annual uplift from Pillar 2.

    That £77 million is not a rounding error. It is not going to be fixed by efficiency savings alone. The General Revenue Reserve, the buffer that has been absorbing shortfalls, is projected to be exhausted by 2031 on the current trajectory.

    The demographic picture makes this worse. The working age population is shrinking relative to the overall population. Three quarters of all States revenue comes from individuals, personal income tax and social security contributions. That tax base is narrowing as it ages, just as demand for health, long-term care and pension expenditure accelerates. The Policy Letter is honest about this: these pressures will continue to grow for several more decades.

    This is the genuine context for what follows. You can disagree with the solution without ignoring the underlying problem.

    What the Package Actually Contains

    The proposed package has five main components. Here is what each actually does.

    1. Income Tax: Lower Rate, Lower Threshold

    The headline change is a reduction in the basic rate of personal income tax from 20% to 15%, applied to income up to £28,000. Income above that threshold continues at 20%. The personal allowance also rises by £600.

    This sounds like a tax cut, and for most earners it is. But the design matters. The 15% band cuts off at £28,000 which is below the median full-time earnings figure in Guernsey. The policy is deliberately redistributive: lower and middle earners gain more than higher earners in percentage terms.

    The net revenue impact is a reduction of £28 million. The income tax reform is not a revenue-raiser, it is the redistributive counterweight to GST.

    2. Social Security: A Restructured System

    The social security changes are more complex and have been significantly moderated from the November 2024 package. Key changes include:

    • A new social security allowance for employed and self-employed contributors, set at £11,122 (currently the allowance for non-employed contributors), with a longer-term ambition to align this with the income tax personal allowance
    • Employer contributions increasing to 7.6% by 2029 (phased from the current 7.1%), payable up to the Upper Earnings Limit of £196,560
    • A new additional rate of 2.5% for employers and self-employed individuals on earnings between the Upper Earnings Limit and £300,000
    • Employee contributions rising to 8.5% from 2028; self-employed to 14.5%; non-employed under pension age to 8.5%; non-employed over pension age to 4%

    One significant change from November 2024: the proposal to apply social security contributions to all income (including rental income) has been deferred. The Policy Letter is candid about why: concern that this would push landlords out of the market, compounding Guernsey’s already serious housing supply problem.

    The net revenue impact of the social security changes is a gain of £2 million.

    3. Transport: Fuel Duty Down, Annual Vehicle Tax Up

    This is a package of changes rather than a single measure. Fuel duty drops by 25%, broadly bringing Guernsey into line with Jersey, an estimated saving of £130–£140 per vehicle per year for private motorists.

    In exchange, a new annual vehicle tax is introduced, covering petrol, diesel, hybrid and electric vehicles, based on weight and emissions. The range is £25 to £280 for private vehicles, with a median charge of around £132.

    A surcharge is also added to first registration duty for private vehicles valued over £50,000 (starting at £2,500).

    The net revenue gain from transport changes is £7 million. The fuel duty cut is the headline that will get the press coverage; the annual vehicle tax is the structural change that matters for the long term, particularly as electrification reduces fuel duty receipts over time.

    4. GST: 3%, From 2028

    This is the most controversial element, and the one that has dominated debate for years. The proposal is a Goods and Services Tax at 3%, to be introduced from 2028.

    This is a reduction from the 5% that was agreed in November 2024, driven by concern about the inflationary impact. At 3%, the modelling suggests a one-off increase in RPIX of around 1.9% at introduction — down from 3.2% under the previous 5% proposal.

    The GST package includes:

    • Uprating of the States Pension, income support and other benefits to cover the increased cost of living, with those increases introduced ahead of the GST
    • An Essential Costs Relief Payment for those on lower incomes not in receipt of income support
    • An International Services Entities (ISE) scheme, mirroring Jersey’s, allowing finance businesses with international clients to pay a fee for an End User Relief Certificate rather than filing full GST returns. Expected to raise £10–12 million annually
    • A commitment not to increase the GST rate before the 2030 assurance review

    The net revenue gain from consumption tax measures is £55 million, the dominant revenue line in the package.

    A two-thirds majority requirement to increase the GST rate in future will also be introduced, providing a structural protection against rate creep.

    5. Corporate Tax: Modest Adjustments Only

    The headline finding from the Tax Review Sub-Committee, chaired by Deputy Charles Parkinson and including three international tax experts, is that fundamental corporate tax reform is not recommended at this time.

    The Sub-Committee considered five options, including a move to a territorial tax regime and a shift from Zero-10 to Zero-15. Both were rejected. A territorial regime would trigger a full review by the EU Code Group, take 12–18 months to resolve, and carry significant risk of business relocation. Moving unilaterally to Zero-15 was modelled to produce minimal net revenue gain once behavioural responses are factored in.

    What is recommended is a set of targeted adjustments:

    • Extending the 10% intermediate rate to apply to the full profits of regulated businesses (not just the regulated activity), aligning with Jersey’s approach (estimated yield: £0.5 million)
    • Extending the 10% rate to prescribed businesses — accountants, legal firms, estate agents registered with the GFSC (estimated yield: up to £2 million)
    • Modest increases to Guernsey Registry fees (estimated yield: ~£0.5 million at RPIX +5%)
    • Further extension to construction and retail deferred until 2030 at earliest

    The net corporate tax gain in the package is £6 million.

    The Sub-Committee also recommends that P&R opens discussions with Jersey and the Isle of Man about a coordinated move to Zero-15 after their General Elections this year — an interesting recommendation that could be significant if picked up.

    The Numbers in Total

    MeasureNet Revenue Impact
    Income tax changes-£28m
    Social security changes+£2m
    Transport taxes+£7m
    GST + ISE scheme+£55m
    Corporate tax adjustments+£6m
    Spending efficiency savings+£20m
    Total~£62m

    Against a structural deficit modelled at £77 million, this package does not fully close the gap. The Policy Letter acknowledges this. That is precisely why the assurance review in 2030 matters, and why the commitment not to raise GST before that review carries real weight.

    What This Package Is, and What It Isn’t

    The political debate will focus on GST. That is understandable as it is the largest single revenue line, and it affects everyone. But framing this as simply “introducing a tax on food and goods” misses the architecture of the package.

    The income tax reduction to 15% is not an afterthought. For a single earner on £28,000, the saving on income tax alone exceeds the estimated annual cost of GST on their consumption. The benefit and pension uprating is front-loaded, it happens before GST is introduced, not after. The Essential Costs Relief Payment is targeted at those not already captured by income support.

    The distributional analysis in the Policy Letter shows that lower and middle income households are, on average, expected to be better off under the full package than they are now. Higher income households are expected to be modestly worse off. That is a deliberate policy choice.

    Whether you accept that analysis depends on whether you trust the modelling, the mitigations, and the political commitment to hold the rate at 3%. Those are legitimate questions.

    What I Think

    The structural deficit is real. The demographic challenge is real. The reserves position is serious. Anyone who believes Guernsey can grow its way out of this problem without broadening the tax base is not engaging with the numbers.

    The balance struck here, lower income tax rates for lower earners, a modest consumption tax, restructured social security, and restrained corporate tax changes, is a considered one. It is not the package I would have designed from scratch, and there are elements I would push back on. But it is a serious response to a serious problem, with a genuine attempt at a progressive tax approach.

    The question the States must now answer is whether they agree. After twelve years of review, the question is no longer whether to act, it is whether this is the right way to act.

    I’ll be watching the debate closely.

    Jon Bond is Founder and CEO of Evans Bond Limited, an accountancy and advisory practice in Guernsey, and principal of Melius Consulting Limited – a business consultancy. He is also a non-executive chairman of CI Co-op and NED at Sark Shipping. The views expressed here are his own.